Sorry to hear, but it seems they worked by the letter, so very little to appeal
Even for cards from the same bank, there seem to be different “levels” of the same card:
My (foreigner) CUBE Visa has a silver “VISA Signature” logo. My girlfriend (Taiwanese) recently had to replace her CUBE visa (she previously had an old Cathay VISA Card) - and they sent her one with a blue “VISA Platinum” logo.
In general, Visa Signature seems to be better (according to Gemini / Google Search, it offers better benefits) - although I don’t know if there are any practical differences between those two cards as they’re both CUBE cards (which should follow the same benefit model) 
With regards to the CUBE card, they seem to offer at least five different “versions” (Mastercard, VISA and JCB with VISA having two different “tiers”):

(Taken from https://www.instagram.com/p/ClIYfOxLBB1/ )
The also seems to be a CUBE VISA Infinite Card - though that one was only available through converting one’s COSTCO card apparently.
They merged lots of things e.g. Costco into CUBE so that’s expected. There’s also CUBE combo that acts as your bank card.
I keep hearing that travel credit cards in Taiwan are much worse than those in the US in terms of earn rates, sign-up bonuses, and redemption value.
For those who have experience with both, is this objectively true, or just perception? Are Taiwan travel cards still worth using if you fly regularly, or is cashback usually the better option here?
Would appreciate real comparisons and opinions. Thanks.
objectively true…
If you play the points game, after just 10 minutes of research you’ll see how bad the Taiwanese cards are compared to American cards.
For starters, the US chase sapphire reserve and American Express platinum give 4-8% points on flights and have no foreign transaction fees.
I didn’t even “boost” the values by converting to “cpp value” via transfer partners or biz plat rebate. Doing that can add an additional 50% resulting in 6-12% value-back from transaction price.
When u play with the revenues of American cards, it’s easy to give incredible perks. Taiwan interchange is lower.
u go to Europe perks and rewards are even worse due to fees caps by the EU.
tbh I’m quite satisfied, once u find the optimal strategy given ur spending patterns, u can still rack up decent amounts of miles, get good lounges access and, the most underrated of all perks, the free drop off and pick up service at the airport. That’s a game changer for me.
Credit card perks in Australia aren’t amazing either, similar to Taiwan.
Maybe the US is the outlier
Do you know about the different levels of Cube cards?
Do you get level 3 immediately once you have 3 million NTD in Cathay United? Or is that still a discretionary decision? And what about the perks that you might or might not get. Anybody with experience on these different levels? I only recently saw that I am level 2 without ever having looked at it, but I guess level 2 doesn’t change anything.
It activates automatically a month after you qualify. I have it but other than the extra 0.3% cashback I don’t use any of the VIP perks.
Just saw this promotion. They limited applications to 1000 per month.
https://www.taishinbank.com.tw/TSB/personal/credit/intro/overview/cg038/card001/
Do you have this @Mataiou? But you are more interested in miles benefits.
What are you talking about? I just got 150,000 Qantas points on signup for one. (Enough for 2 economy return trips to Manila from Adelaide)
Also on spend in Australia the real trick is utilising Woolworths membership and gift cards. I’m averaging about 5+ Qantas points a dollar spent at Woolworths by purchasing gift cards using my credit card at 3 Qantas points for each dollar plus 1.25 Qantas point per dollar spent on the card plus I have everyday rewards plus and with boosting I’m getting about 1.5 Qantas points (conservative estimate) on the everyday rewards
Each Qantas point is worth about 3 cents for economy flights so 3X5 =15 cents per dollar spent at big w and Woolworths (which is where most of my spending is)
Don’t have the Jko card.
I really look only at mile benefits. Just scored a TPELHR one way on Eva in business for 2k NT (taxes) in may.
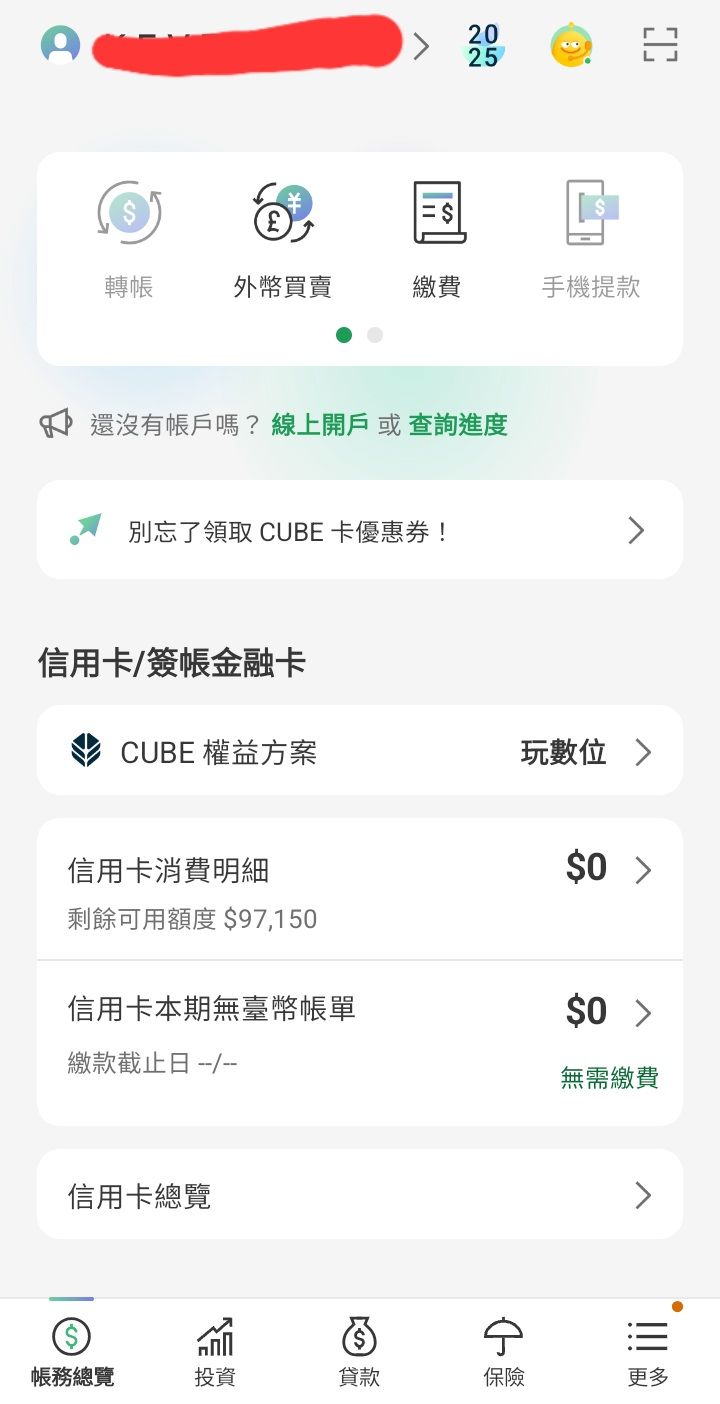
I received my Cathay Cube card last Thursday. I selected the 玩數位 plan, which is the digital plan, registered the card to my Google Play account, and purchased some in-game add-ons with it, but when I checked my app
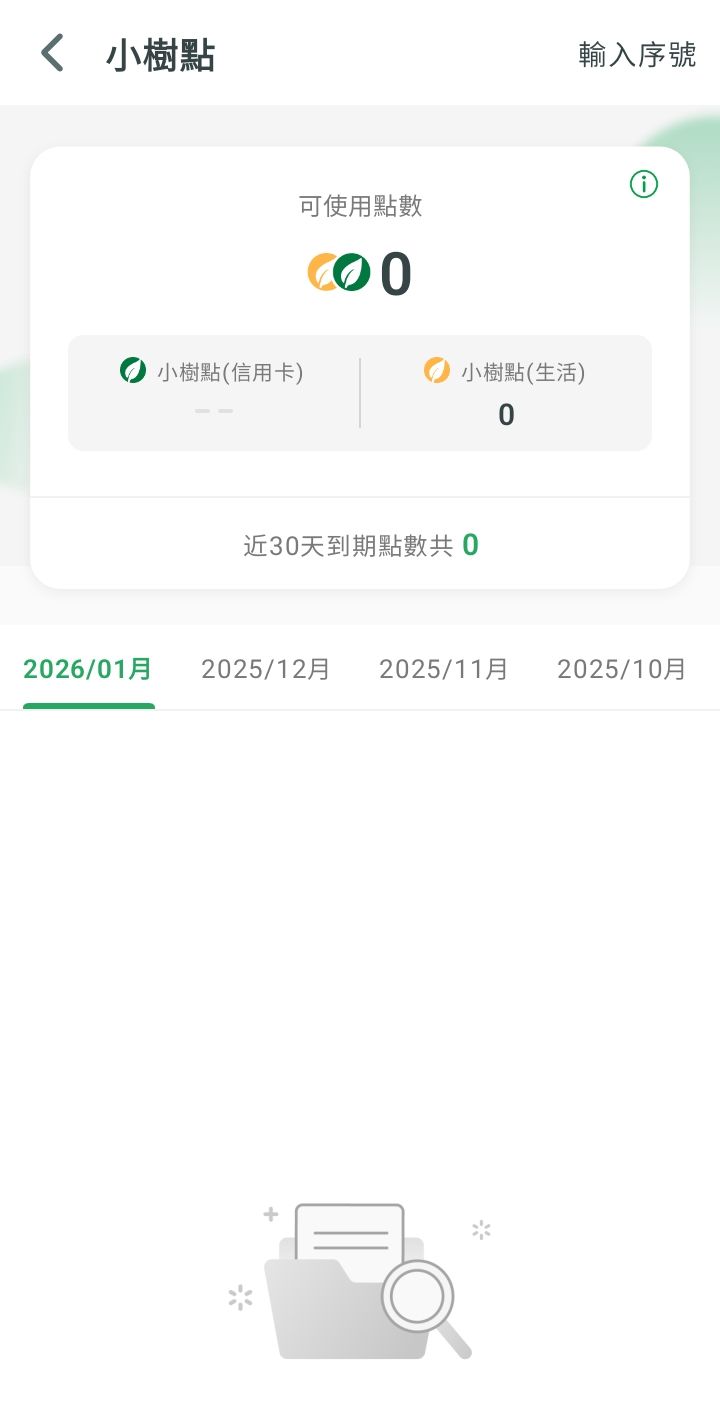
Do the tree points show up immediately? Or are they only visible in the app after they accumulate and calculate all of your purchases at the end of your billing cycle?
Shows up at 5pm on the day[1] the transaction posts. Get the rewards app for all the details.

If the category was wrong you’ll see 0.3% cashback here which could be 0 points when the amount is low enough.
it shows up on this day, but it shows as posting the previous day ↩︎
Thanks for the reply! I only have the “main” app (Cathay Shihua), and right now it’s under maintenance, but I’m pretty sure yesterday evening, when I checked the app, I still had 0 points (I purchased the add-ons on Friday morning). The purchases are listed in the purchase history though. I’ll check it in the app you recommended, it’s also under maintenance right now.
By the way, I noticed your cashback rate is 3%. I checked the CUBE website, and it said that I need to be a VIP member to get that bonus. How did you get it?
3% is level 2, 3.3% is level 3 (VIP).
It doesn’t show up in both apps. The transactions do though. I’m not sure if I checked the wrong page/window.
From the rewards app:

Didn’t even register any of the transactions.
From the main app, you can see I’ve selected the 玩數位 plan
All of the transactions were from the same game, but only the first one showed “Google” “Game name”. The others only showed “Online Transaction”

When you clicked on the transaction, it didn’t show anything. It didn’t even show 0.3%.

Damn you need 3M for VIP? I think ESUN only requires 300k for their highest level.
That didn’t post yet. You’re looking at the 即將消費明細 tab which means unposted transactions.
How do you “post” the transaction?. The other tab “未出帳明細” is completely empty.
Or is the process automatic, like when it’s done (whenever that is), all the transactions in 即將消費明細 will be displayed in the 未出帳明細 tab?
While we’re at this: Recently booked a hotel but they charged the deposit as an home appliance purchase (?), so 0.3% instead of 3%…
Any experience on how accommodating Cathay Bank is these days in still crediting the points when calling them…?